


DSCR Loans in Florida: No Income Verification Mortgage for Real Estate Investors
Invest in real estate with confidence. The Debt Service Coverage Ratio (DSCR) Loan allows investors to qualify based on the property’s cash flow, bypassing the need for personal tax returns, W-2s, or employment verification.
How does a DSCR loan actually work?
Traditional mortgages are often restrictive for successful real estate investors who use complex tax strategies or who are self-employed. The DSCR mortgage program is a Non-QM solution specifically designed to put the focus on the asset's performance rather than the borrower's personal income.
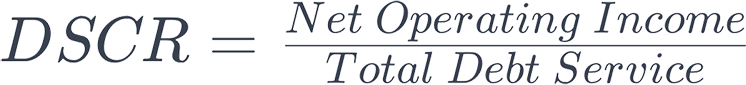
How is a DSCR loan calculated?
The core of the program lies in a simple calculation:
PITI includes Principal, Interest, Property Taxes, and Insurance.
What DSCR ratio do I need?
- DSCR ≥ 1.00: The property is cash-flow positive (rent covers 100%+ of the mortgage). Best rates available.
- DSCR < 1.00: Often called "No-Ratio" loans, allowing qualification with lower cash flow. Requires a higher down payment/LTV.
- DSCR = 0.00: Applicable for investors with high reserves, meaning no cash flow is needed, but typically requires 30–40% down.
Why use this instead of a conventional loan?
Do you look at my personal income?
No W-2s, tax returns, pay stubs, or personal Debt-to-Income (DTI) calculations are required for approval.
Can the property qualify on its own?
The property's estimated market rent is the primary qualification factor, making it ideal for self-employed borrowers.
Can I refinance or pull cash out?
Available for Purchase, Rate-and-Term Refinance, and Cash-Out Refinance to pull equity for new deals.
How many properties can I finance?
Rapidly expand your portfolio without personal DTI restrictions. Buy, refi, and repeat without the traditional paperwork.
What do I need to qualify?
What properties are eligible?
The DSCR program is strictly for non-owner-occupied, income-producing properties. Eligible property categories include:
- Single-Family Residences (SFR) and Townhomes
- 2- to 4-Unit Multi-Family Properties (Duplexes, Triplexes, Fourplexes)
- Condominiums (Non-warrantable condos may be considered)
- Short-Term Rentals (Airbnb/VRBO) using calculated short-term rental income data.
- Exclusion: Owner-occupied primary residences or true second/vacation homes do not qualify.
What do you need from me?
While personal income is ignored, standard underwriting still applies to the borrower's stability:
Min. Credit Score
640
Min. Down Payment
20%
Required Reserves
6–12 Months PITI
Pre-Payment Penalty
Varies (Often None)
Can I use a DSCR loan if my Florida rental does not cash flow yet?
Sometimes. Plenty of DSCR programs want the rent to at least cover the payment, a ratio of 1.0 or better. Others will go under that and price for the gap, leaning on your reserves and the strength of the file. A property that pencils a little short is not dead on arrival.
The real work is knowing which lender's floor your number clears. A figure that stalls at one lender clears at the next. That is the whole point of shopping it around.
Can short-term rental income from Airbnb or VRBO qualify a Florida property?
For the right lender, yes. Florida runs on short-term rentals, and some DSCR programs will qualify a property on projected or actual nightly income instead of a twelve-month lease. Expect to document it differently: a market rent schedule, a booking history, or a third-party projection, depending on the program.
The catch is that not every lender allows short-term income, and the ones that do each write their own rules around it. Your property, your county, and your booking record decide which door opens.
Can I hold the property in an LLC or other entity?
Yes. Most DSCR lenders expect title to sit in an LLC, which is how experienced Florida investors handle liability and keep the rental books separate from their own. You hand over the operating agreement and the articles, the members sign a personal guarantee, and the file moves.
Holding in an entity usually helps a DSCR loan along rather than slowing it. A conventional loan would drag the whole thing back onto your personal name and your personal ratios.
A bank denied me on an investment property. Does that denial carry into DSCR?
Not usually, because the bank ran a different test. Conventional investment denials tend to trace back to your personal debt load, the number of properties you already finance, or an overlay the bank stacked on top of the guideline. DSCR sets your personal income aside and reads the property.
A file that died on the conventional side because you already carry five mortgages can be a clean DSCR approval. Wrong tool the first time, that is all it was.
How many Florida investment properties can I finance before conventional runs out?
Conventional financing tightens once you pass a certain number of financed properties. Reserves climb, the paperwork gets heavier, and eventually the door shuts. DSCR does not run that portfolio counter, because each loan stands on its own property's income.
Investors pushing past four or five doors in Florida tend to shift to DSCR right around there, and stop fighting the count.
Do DSCR loans work for Florida condos, non-warrantable condos, and condotels?
Some do. A warrantable condo is easy. Non-warrantable condos and condotels, which line the Florida coast, are where most lenders bail, and a handful of DSCR programs step in instead.
This is the deal where the wrong lender burns two weeks before declining. Knowing up front which programs will actually underwrite a given building is the difference between a close and a dead file.
How fast can a DSCR loan close in Florida?
Often quicker than a conventional investment loan. There are no tax returns, no pay stubs, and no employment calls to sit through, so the clock runs on the appraisal, the rent analysis, and title.
On a competitive Florida contract, that kind of speed gives you an edge. Your actual timeline depends on your file, so ask us directly instead of relying on a generic estimate.
Are DSCR loans available to foreign national investors buying in Florida?
For certain programs, yes. Florida pulls heavy overseas money, and some DSCR lenders keep foreign national guidelines that skip U.S. credit and U.S. income entirely. The terms sit differently than a standard DSCR loan, and the paperwork is specific to each program.
It is a legitimate path. It is also one a branch teller has never processed, so where you bring the file matters more than usual.
I am a Realtor or wholesaler with an investor client. Can you place the loan?
Yes. A fair share of these files arrive through Florida agents and wholesalers whose investor got stonewalled somewhere else. Jason reviews the deal personally, tells you fast whether it places and roughly where, and carries it to closing. Nobody hands it off midstream.
If you are sitting on a contract a lender already killed, that is the one to call about.
Can I use a DSCR loan to refinance a Florida property I bought with hard money or cash?
Yes, and it is the backbone of the buy, rehab, rent, refinance play. You buy with cash, hard money, or a bridge, fix the property, get a tenant in, then refinance into a DSCR loan to pull your capital back out and hold.
Two things swing it: how long the lender wants you to season before they use the new appraised value, and how the rent lines up against the new payment. Both move by program, so pin them down before your cash is tied up in a deal.
DSCR loan or hard money: which does a Florida investor actually need?
Different jobs. Hard money and bridge loans are fast, expensive, short-term money for buying and rehabbing. DSCR is patient thirty-year money for holding a stabilized rental. Most working investors run both in sequence: buy with the first, refinance into the second.
The costly slip is sitting in hard money after the property is leased and performing. That is the moment to move.
What reserves do DSCR lenders want on a Florida rental?
Most programs want a few months of the property's payment sitting in reserves, and the exact figure shifts with your credit, the loan size, and whether you run the place short-term or long-term.
Reserves are a lever. A ratio that reads a little tight can still clear when the cash behind it is deep. Plenty of investors do not realize how much that one number can move a file.
Can a first-time investor with no landlord history use a DSCR loan?
Often, yes. Because DSCR grades the property instead of your paycheck, a lot of programs do not require prior landlord experience, though a few charge slightly for it or want a bit more down. Your first Florida rental can be a DSCR loan.
What counts is that the numbers on that specific address work, and that the file lands with a lender whose first-timer rules are friendly.
Ready to Scale Your Portfolio?
Whether you’re buying your first investment property or expanding a multi-property portfolio,
the DSCR loan offers the streamlined process you need.
Work with a lender who understands real estate investment strategies.
Contact Jason J. Sarji and the Team Today: 📞 888-601-8344 | 954-390-7994 | NMLS #374739.
Want to know which one fits you best?
One call, under ten minutes. No application, no credit pull. You'll know more than you did this morning.
AAA Capital Funding, Inc. · NMLS #374739 · Jason J. Sarji, NMLS #374700